
If you’ve ever typed “how much personal loan can I get on my salary” into Google, you already know the search results don’t always agree with each other. One site says one number, another says something completely different, and none of them quite match your actual pay cheque. That’s because a personal loan on salary isn’t calculated the way most people assume — it’s not a flat multiple of your income, and it never comes down to salary alone.
Let’s walk through what genuinely decides your eligible amount, so you’re working with real factors instead of a number pulled from a generic table.
Why a Personal Loan on Salary Isn’t Decided by Salary Alone
It would be simpler if lenders just said, “Earn this much, get this much.” But it doesn’t work that way in practice. Two people earning the exact same amount can walk away with very different offers, because the lender is weighing several things together, not just the figure on your payslip.
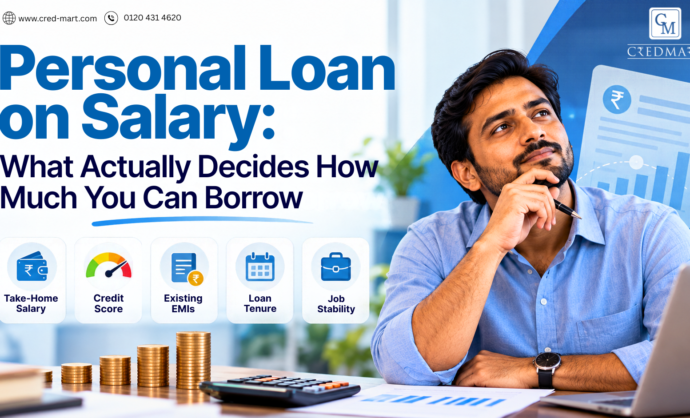
The biggest factor is something called the Fixed Obligation to Income Ratio, or FOIR. In plain terms, your total monthly EMIs — including the new loan — usually shouldn’t cross around 50-60% of what you take home. This single ratio is the main reason your eligible amount can vary so much from person to person, even at identical income levels.
The Real Factors Behind Your Personal Loan on Salary Eligibility
Your take-home pay matters more than your CTC on paper, since lenders work with what lands in your account after deductions. Existing EMIs — a car loan, a home loan, or a heavy credit card bill — eat into the room you have for a new one. Your credit score plays a bigger role than most expect; a score above 700 tends to unlock both a higher amount and a better rate. Tenure matters too — a longer tenure lowers your EMI, which can raise what you qualify for, though you’ll pay more interest overall. And your job stability, including how long you’ve been with your current employer, quietly factors into how lenders view the risk.
How a Personal Loan on Salary Plays Out at Different Income Levels
People often search for their exact income bracket, so let’s address that directly, without pretending there’s a fixed number attached to each one.
On a ₹20,000-₹25,000 salary, your FOIR headroom is naturally tighter, so keeping existing EMIs low matters more here than at higher income levels. A clean credit history can make a real difference in this bracket.
On a ₹30,000-₹40,000 salary, lenders typically have a bit more flexibility, and borrowers in this range often benefit from choosing a slightly longer tenure to keep the EMI comfortable.
On a ₹50,000+ salary, you usually have more negotiating room, and factors like credit score and existing obligations start to matter even more than the income figure itself, since most lenders are already comfortable with the income level.
In every bracket, the pattern is the same: income sets the ballpark, but your credit profile and existing debts decide where exactly you land within it.
Ways to Improve Your Personal Loan on Salary Eligibility
If your first loan check is lower than expected, you can improve it by partially paying down a small existing loan to increase your FOIR, boosting your credit score by even 50 points; choosing a longer tenure to lower EMIs and increase eligibility; adding a co-applicant with a steady income; and spacing out loan applications to avoid multiple hard enquiries that can negatively impact your score. If comparing lenders on your own feels like a lot of back and forth, that’s exactly where Credmart helps — we check your profile against multiple banks and NBFCs at once, so you get a clearer picture instead of guessing which one will approve you.
Mistakes That Quietly Hurt Your Personal Loan on Salary Application
A surprising number of rejections come from avoidable slip-ups, not genuinely poor eligibility. Applying without checking your credit score first is common — people are often unaware of an old default on their report. Underestimating existing EMIs is another. Applying to multiple lenders at once can look like financial stress rather than genuine need. And incomplete documentation often pushes lenders toward a conservative offer, simply because they don’t have your full picture. None of these are hard to avoid once you know they matter.
Documents to Keep Ready for a Personal Loan on Salary Application
Salary slips from the last three to six months, bank statements showing salary credits, PAN and Aadhaar for identity checks, Form 16 or ITR if requested, and a clear list of existing loans or credit cards. None of this changes your eligibility on its own, but it means the lender works with your full picture instead of a conservative guess.
How to Find Your Actual Personal Loan on Salary Amount
Since your eligible amount really comes down to a combination of factors, the only reliable way to know it is to check directly — either with a lender or through a proper eligibility calculator that factors in your income, obligations, and tenure preference. You can do exactly that on Credmart’s personal loan page, where your details are checked against our partner banks and NBFCs instead of a generic estimate.
For the regulatory context behind why lenders assess applications this way, the Reserve Bank of India’s guidelines on responsible lending are worth a look.
F&Qs About Personal Loan on Salary
Does a personal loan on salary depend only on income?
No. Income sets the starting point, but your credit score, existing EMIs, job stability, and chosen tenure all combine to decide your actual eligible amount.
Can I get a personal loan on a low salary?
Yes, many lenders offer personal loans starting from modest income levels, though the eligible amount depends heavily on your credit profile and existing obligations, not income alone.
Does credit score really change the loan amount?
Yes, significantly. A score above 700 usually means access to a higher amount and better rate, while a weaker score can shrink both or affect approval altogether.
What’s the fastest way to improve my eligibility?
Paying down existing EMIs and improving your credit score tend to have the most noticeable impact, followed by choosing a longer tenure or adding a co-applicant.
The Bottom Line on Personal Loans on Salary Eligibility
Understanding how this is actually assessed helps you walk in with realistic expectations instead of guesswork, and that alone can help you avoid an avoidable rejection that dents your credit score. The real number only comes from checking your specific profile, so that’s always a better next step than relying on generic averages.
Check your personal loan eligibility with Credmart and see exactly where you stand, based on your income and what our partner lenders are currently offering.
Apply for a Personal Loan With Minimal Docume
Looking for a personal loan with minimal documents in D...
May 28, 2026


